
7 Affordable Home Ownership Paths That Beat Rising Housing Costs
Last Updated: November 4, 2026
Quick Summary
Affordable home ownership in 2026 works best when you control the biggest cost lever: the home itself. Manufactured home floor plans, from 1-bedroom ADUs to 4-bedroom family models, plus flexible manufactured home financing, let you match a home to your real budget instead of a bidding war.
- Homes listed for sale affordable to households earning $75,000 or less were down 60 percent in March 2026 versus March 2019.
- Only 17% of voters say now is a good time to buy, though 85% still call owning a home essential.
- Track four numbers: monthly payment versus income, your credit profile, total delivered and set cost, and land status.
- Mortgage lenders generally use mortgage-specific scoring versions, so your app score may differ from the lender’s.
- File credit report disputes early, since disputes take time to investigate before a mortgage application.
Table of Contents
- Why Affordable Home Ownership Is Harder Than Ever
- Manufactured Home Floor Plans That Fit Real Budgets
- Financing a Manufactured Home Without Perfect Credit
- Customizable Manufactured Homes: Style Without the Upcharge
- ADU Home Options for Landowners and Multigenerational Families
- What to Ignore When You Research Affordable Housing
- Request Your Patriot Homes Quote and Pricing Matrix
- Frequently Asked Questions
Why Affordable Home Ownership Is Harder Than Ever
Affordable home ownership has rarely felt this far out of reach.
The National Association of Realtors 2026 affordability findings show only 17% of voters say now is a good time to buy, down from 69% in 2013.
At Patriot Homes, we hear that frustration every day. First-time buyers can find a same-topic guide in our affordable manufactured homes for first-time buyers article.
Below, we break down seven paths that actually work in 2026, from floor plans to financing. And if you want numbers for your specific situation, our 24/7 team is one call away at (888) 765-1776.
Manufactured Home Floor Plans That Fit Real Budgets
Manufactured home floor plans are the single biggest lever you control on cost. Square footage drives price. Our lineup runs from compact 1-bedroom designs to full 4-bedroom family models.
Here is how we think about matching a plan to a buyer:
- 1-bedroom: retirees, single buyers, and downsizers who want low upkeep
- 2-bedroom: couples and small households watching every dollar
- 3-bedroom: growing families who need space without a second mortgage
- 4-bedroom: multigenerational households pooling incomes
From 1-Bedroom ADUs to 4-Bedroom Family Models
The right size is the one you can pay off comfortably, not the biggest one you can qualify for. A smaller plan with good finishes can be a better fit than a larger plan you stretch to afford. For families comparing options in detail, our guide to affordable manufactured homes for families walks through layouts room by room.
Financing a Manufactured Home Without Perfect Credit
Financing a manufactured home is more flexible than most buyers expect. You do not need perfect credit or a huge cash reserve to start. Several loan structures exist for manufactured housing, each with its own rules and requirements. But the credit conversation deserves more than a shrug, because your score drives your interest rate, your down payment, and which loan programs stay open to you.
The Credit Moves That Actually Move Your Score
Most buyers have heard the generic advice. Here is what each move actually does before a mortgage underwriter sees it:
- Check your credit report for errors. Pull all three bureau reports and dispute anything wrong, a collections account that was paid, a duplicate balance, an address that is not yours. Errors are common and they cost you points.
- Pay every bill on time. Payment history is the single heaviest factor in a consumer score. One 30-day late can linger for years.
- Reduce your debt-to-credit ratio. This is your credit utilization, balances divided by limits. Keeping utilization low, both on each card and across all cards, generally helps your score. Paying a balance down before the statement closes matters more than paying it off after.
- Avoid applying for new credit. Each application triggers a hard inquiry. A cluster of them in a short window reads as risk.
- Maintain a healthy credit mix. A car loan, a credit card, and a retail account used responsibly show you can handle different kinds of debt.
- Understand credit history length. The age of your oldest account counts. Closing an old card to “clean up” can shorten your history and hurt you.
- Build from scratch if you have no file. A secured card, a credit-builder loan from a community bank or credit union, or a small store card used and paid in full each month gets a thin file moving.
Your Consumer Score Is Not Your Mortgage Score
This is the part most guides skip. The score you see in a banking app is usually a consumer FICO or VantageScore. Mortgage lenders generally use mortgage-specific scoring versions, so the score you see in an app may differ from the one a lender uses. Those versions weight things differently, which is why a buyer can see a 720 in an app and get quoted off a 690. Ask any lender which scores they pulled and from which bureaus before you assume your rate.
The Seasoning Lag Nobody Warns You About
Paying down a card does not instantly raise the score your lender sees. Statements have to close, the bureau has to receive the updated balance, and the scoring model has to refresh, which takes time. If you are planning to apply, make your payoff moves well before you apply.
Disputes Take Time, Plan Around It
A credit report dispute is not instant. Disputes take time to investigate, so file them early. If a mortgage application is on the calendar, file disputes early and keep your documentation, rather than filing the week you want pre-approval.
The Authorized User Shortcut Can Backfire
Adding yourself as an authorized user on a relative’s seasoned card can lift a thin file.
A common mistake is assuming a low score ends the conversation. It usually just changes which loan fits. Lenders look at payment history, debt load, and how much you can put down.
Watch out: applying to several lenders in one week can ding your score with multiple hard inquiries. Get pre-qualified with one lender first, then compare.
For a full breakdown of credit requirements and options, read our guide on financing manufactured homes with low credit.
Customizable Manufactured Homes: Style Without the Upcharge
Customizable manufactured homes let you choose the bedrooms, bathrooms, and finishes that fit your lifestyle.
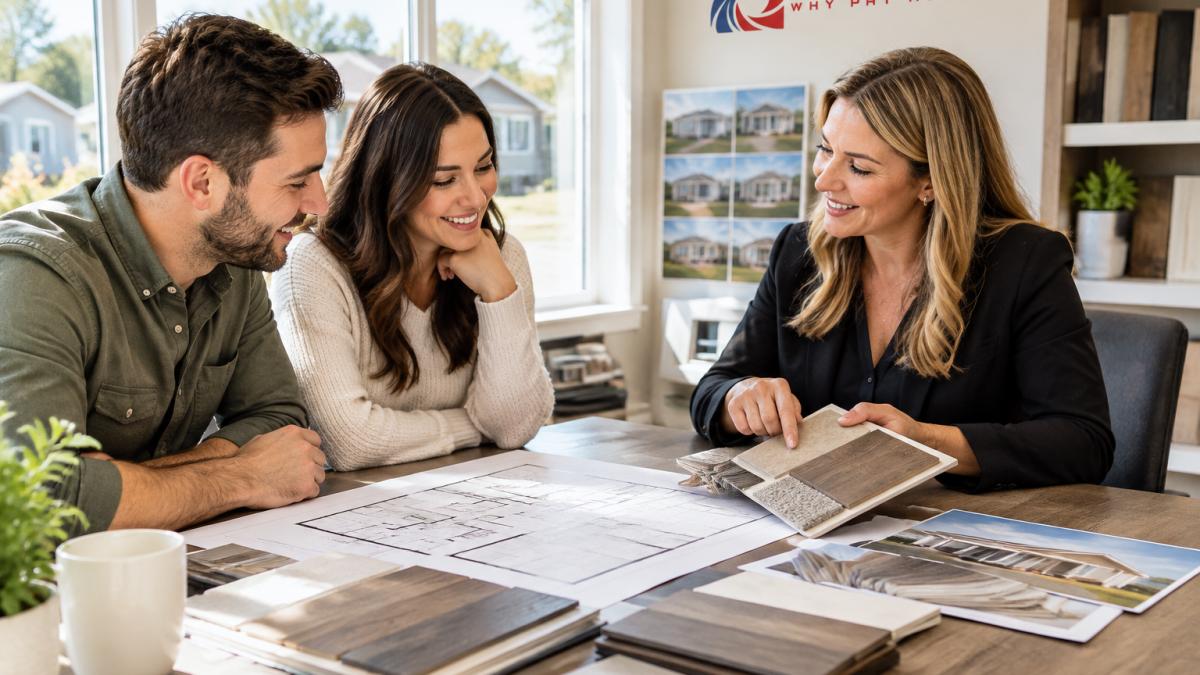
Our core promise is simple: why pay more when you can have quality, style, and affordability all in one?
Want to see how custom building works in this part of the country? Our custom manufactured home builders guide covers the process from first sketch to delivery.
ADU Home Options for Landowners and Multigenerational Families
ADU home options let landowners add a second living space without buying more land. If you already own property, a manufactured ADU can house aging parents, adult children, or renters who help cover the mortgage.
We proudly serve local homeowners across California, Arizona, Idaho, and Nevada with custom manufactured and modular options. Call our team to discuss placing a home on land you already own.
A second unit can add housing flexibility and may provide rental income. It also keeps multigenerational families close without sharing one kitchen.
What to Ignore When You Research Affordable Housing
Much affordable housing research is written for policymakers rather than buyers. You will wade through reports on rental shortages and subsidy programs that say nothing about your down payment. Here is how to filter it fast, and what to replace it with.
Skip These, They Will Not Help You Buy
- Rental shortage studies. Useful for city planners, irrelevant to your mortgage.
- Subsidy program announcements that do not list eligibility in plain language or a phone number to call.
- National median price headlines. A national number tells you nothing about what a home costs on your lot in your county.
- “Best states to buy” listicles built on averages that ignore land status, utility hookups, and delivery.
A useful stat to keep in perspective: the National Low Income Housing Coalition’s 2026 Gap Report finds a shortage of more than 7.2 million rental homes affordable to extremely low-income renters. That is a policy problem. Your problem is narrower and solvable.
Track These Instead, The Four Numbers That Decide Your Deal
- Monthly payment versus income. Not the sticker price, the all-in monthly figure including loan, taxes, insurance, and any land or community costs.
- Your credit profile and which loans fit it. A middle mortgage score in the 600s opens different doors than one in the 700s. Know yours before you shop.
- Total delivered and set cost. The home, transport, foundation, utility connections, and setup. A quote that stops at the factory gate is not a quote.
- Land status. Do you own the land, are you buying it, or are you leasing a lot in a community? Each path changes your financing and your long-term cost.
The Research Habit That Saves the Most Money
Ask every source the same question: what does this cost me per month, delivered and set, on my land? If a report, article, or salesperson cannot answer that, it is background noise. A smaller floor plan with good finishes, placed on land you already hold, can be a comfortable fit for your budget.
We proudly serve local homeowners across the region with custom manufactured and modular options, from 1-bedroom ADUs to spacious 4-bedroom models, and we are here to help in every city and county we serve, and likely more. For a regional view of what is working, our overview of affordable housing solutions for Western states covers programs, financing, and land costs in one place.
Filter out the noise and track the four numbers that actually decide your deal.
| Track this | Why it matters |
|---|---|
| Monthly payment versus income | All-in monthly figure including loan, taxes, insurance, land or community costs |
| Your credit profile and which loans fit it | A middle mortgage score in the 600s opens different doors than the 700s |
| Total delivered and set cost | Home, transport, foundation, utility connections, and setup |
| Land status | Own the land, buying it, or leasing a lot changes financing and long-term cost |
Request Your Patriot Homes Quote and Pricing Matrix
The fastest way to learn what affordable home ownership could cost you is to ask. We will walk you through floor plans and customization options, and provide a pricing matrix built for your budget.
Call our 24/7 team at (888) 765-1776 for pricing, customization questions, or immediate help. You can also request a quote from our website and we will follow up fast.
We are here to help in every city and county we serve, and likely more.
Frequently Asked Questions
What are the benefits of choosing a manufactured home for affordable housing?
Manufactured homes can be a more affordable path to homeownership than many site-built options. Patriot Homes takes it further with customizable layouts, finishes you pick yourself, and a 24/7 team at (888) 765-1776 that walks first-time buyers through every step. The result is affordable home ownership without the compromises people expect from a starter house.
How does the customization process work for new manufactured homes?
You start with a floor plan, then choose bedrooms, bathrooms, and finishes. Patriot Homes offers models from 1-bedroom ADUs to 4-bedroom layouts, so the process starts at your budget rather than a fixed package. Call our team to discuss what your selections mean for your total. Call (888) 765-1776 or request a quote on the website to see current options and pricing.
Can I find affordable home ownership options in my local area?
Patriot Homes serves homeowners across California and surrounding Western communities, including many counties and cities throughout the region. Local availability depends on your land situation, zoning, and the model you choose. The fastest way to confirm what works for your address is to call (888) 765-1776. The team can tell you which floor plans and ADU home options fit your area and connect you with a quote.
How do I start the process of purchasing a manufactured home with Patriot Homes?
Call (888) 765-1776 or request a quote from the website. Call our team to discuss your land, budget, and timeline, and to explore manufactured home floor plans. The team is available 24/7, so you can start the conversation whenever it suits you, even before you have financing fully sorted.
Rising costs will not wait, and neither should your plan. Call Patriot Homes at (888) 765-1776 today and let our 24/7 team build your pricing matrix, walk you through customization options, and match you with a floor plan that fits your budget. Why pay more when you can have quality, style, and affordability all in one? Get started with Patriot Homes and take the first real step toward affordable home ownership.
